We recently talked about what stock valuation means. Then we realized how interesting this topic is, how to value a stock. Do we want to determine its price, its entry point, or its category? We debated this for a while, and then we decided to try to answer these questions. You can learn what growth stocks are, value stocks, dividend stocks, when to buy or sell them, and how to check if a stock is trading at fair value.
Stock valuation: do we need labels?
You've probably heard the term "growth stock" when it comes to stock valuation, but the term "value-based" is also used to refer to stocks that are believed to have some deeper underlying value. Then there are the disruptive, or industry-reforming, stocks, dividend stocks, and I could go on and on.
💡The literature does not distinguish between such categories, these are just fancy labels. On the one hand, there is no basis for categorizing companies into these categories, and on the other hand, all such sets are relative.
Microsoft (MSFT), which is growing at 20% per year, but pays dividends, and practically dominates the operating system market, which category does it belong to? Investors often have different expectations when it comes to the valuation of labeled stocks. It's okay for a growth stock to trade at a higher value than a value stock, and there are other similar misconceptions in the market.
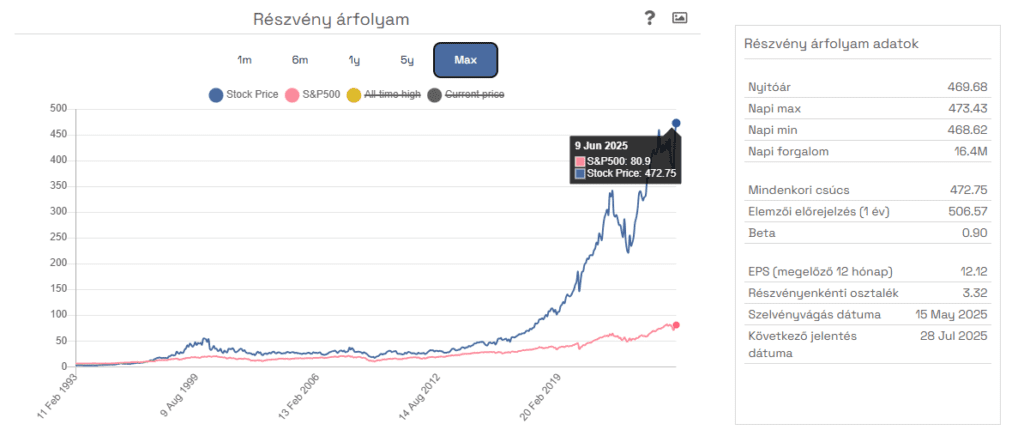
💡The other problem is that a company can simply grow faster in some stages of its life cycle than later on. This is usually, but not always, because it is not yet constrained by the huge market size.
Later, however, it becomes a real cash cow, which is also not a bad stage, just different from the previous one. To be able to identify these states, you need to understand the corporate life cycle model. You can also use market capitalization as an approximation for this, and I will say a few words about that too.
Stock valuation: the corporate life cycle model
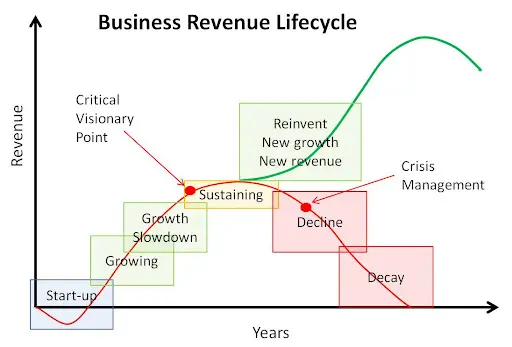
The company life cycle model is very easy to understand. Think about how a company grows. This is best experienced by following a startup, so you won't really come across the first 3 points below. I've written several articles about startups, you can access them here: startup articles.
Business life cycle phases
- 🌱The garage company is formed. There is an idea, a family throws money together, they create a prototype product or service (MVP= minimum viable product)
- 🌿the company is financed by an investor, a venture capital fund or they start crowdfunding and obtain the necessary capital
- 🌳the company has gone through several rounds of financing and is starting to generate profits, which it is investing in growth
- 🍂the startup grows big enough to go public. —> IPO
- 📈the company begins to grow on the stock market, which is reflected in additional revenue and profit
- 📉in the mature stage, the company's growth slows or stops, it dominates the market and prints money
- 🌱renewal, if the company is able to do so
- ⚰️decline
📌In practice: Since I have also built a startup portfolio in addition to the stock portfolio, I can confidently say that the death rate of companies in the first 2 steps is extremely high, around 90%. Therefore, you should not really want to invest at this time, unless you are looking for a particularly high risk/return ratio and have a lot of money to burn.
Market capitalization
Listed companies enter the stock market after the fourth phase. Of course, there are private companies that never go public. One example is IKEA, which can easily be called a mega-corporation with its multi-billion dollar valuation. The point is that market capitalization can usually be used to infer which phase of its cycle a company is in. The problem is that in a declining phase, the value of the company is obviously decreasing, and therefore the price of its shares. As a result, market capitalization will naturally also fall. However, if it is renewed, there is a good chance that the price will start to rise again, meaning that the valuation of the shares will also change.
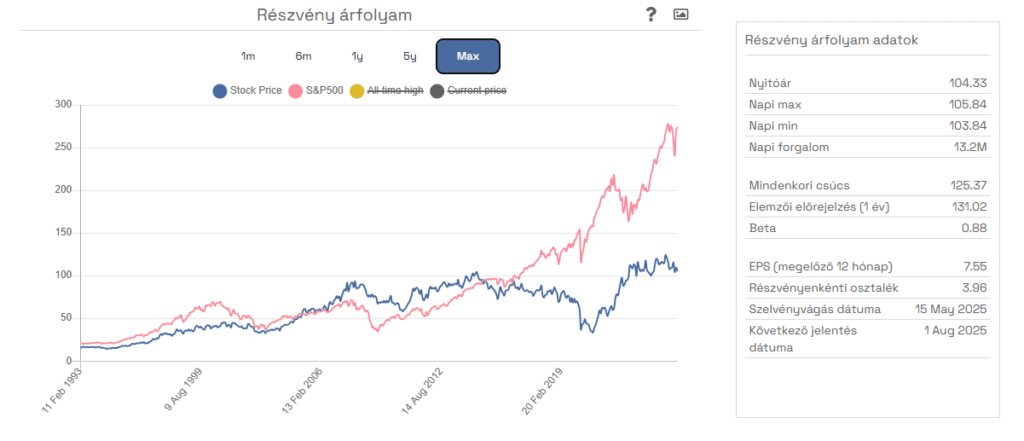
Let's look at an example of each. Exxon Mobil (XOM) peaked in 2012, and has not been able to grow since then, as has the entire industry. It is not really clear whether the share price can move upwards, it has been sideways since about 2007, but there are obviously swings up and down. Tobacco companies have similar problems. However, Philip Morris (PM) seems to be reversing the trend, with their lower-risk products already generating nice revenue, offsetting the decline in traditional products. Microsoft (MSFT) is a very prosperous company, its market capitalization has skyrocketed, and the share price chart is exemplary, the valuation of such shares always increases relatively quickly.
The above labeling can actually be applied based on the current life cycle of the company. If it is still small and growing quickly, it is a growth stock. If it is an older company and is creating a lot of value, such as through dividends, share buybacks, debt reduction or other forms, it is value-based, and so on.
😭Unfortunately, it is precisely because of this categorization that investors often expect different things from certain securities, even though, as I have already emphasized, these are just labels and should not play a role in evaluating a company.
Stock valuation: what is the appropriate market capitalization?
The answer to this is that there is no real good answer. I have written in startup articles that I don't really like startups that have been stagnant for 5-6 years. This also means to me that they are unable to grow in the early stages of their life cycle, which does not bode well for the future.
Fortunately, there are relatively few companies on the stock market that have a truly small capitalization, but of course you can find penny stocks as well. I don't hold such stocks because these companies are typically not big enough to compete with their competitors. PetMed Express (PETS) was also like that recently, it is worth reading their Q reports to see what management says, for example, about how much their competitors spend on advertising and how much they spend. To give an exception, the market capitalization of Computer Modelling Group in July 2025 is approximately 500 million USD, you can read their analysis here: Computer Modelling Group Stock Analysis (TSX:CMG).
The reverse is not necessarily true. In fact, the companies with the largest capitalizations are very prosperous companies, for example: Microsoft (MSFT) or Alphabet (GOOGL). Here too, it would be difficult to differentiate and squeeze these companies into individual categories, but what is apparent is that most of them are capable of the renewal discussed in point 7. Or at least to grow all kinds of wild shoots, since both Microsoft and Alphabet have, for example, cloud services and artificial intelligence.
Valuation of shares based on price
It would be obvious, and many people do it incorrectly, to look at a stock's price chart and make decisions based on that. If it has fallen a lot, it is cheap, while if it has risen a lot, it is expensive. This is a completely incorrect conclusion, but it is psychologically very stressful to invest in a paper that has already risen significantly. Even if the stock itself is still trading below its fair value. I will show you two charts that illustrate the above problem. On the left, the Boston Beer Company (SAM), while on the right is Pfizer (Pfe) stock price chart.
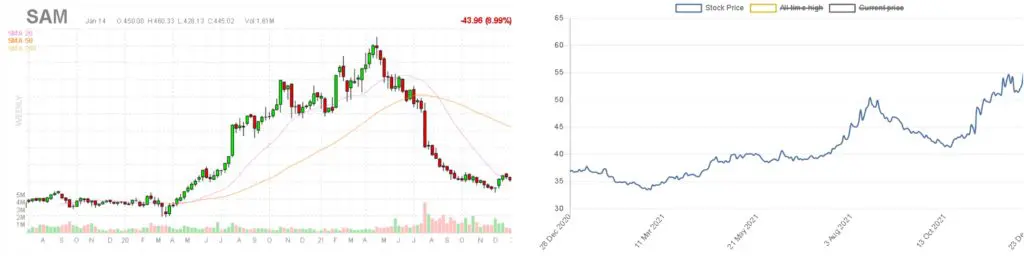
The images above are from 2021 and are instructive snapshots of the past. I'll start with SAM because it has fallen a lot, costing about half as much as its 52-week high a year ago. Let's ask the question, is this stock cheap now? The answer is that it cannot be decided based on these. Because there is no way to conclude from the price movement what underlying event caused this movement. To do this, you need to fundamentally analyze the company and look at what changes have occurred in the company from a qualitative perspective. Another example is Alibaba (BABA) case, where political risks increased significantly, so it fell by almost 66%, and then started to rise again.
The case of SAM
Boston Beer Company was so incredibly expensive in 2021 because the market priced in the significant growth premium of this market segment. The company was strong in the so-called hard seltzer segment, which are actually alcoholic soft drinks. Then, as the quarterly reports came out, it turned out that it was not growing nearly as much as everyone had previously thought. This led to panic selling, which drove the share price below its then-Morningstar fair value, which was $1030. In other words, the stock was on a huge roller coaster. How much is it at the end of July 2025? $206, one-fifth of its peak. The future is always questionable, of course, but as you can see, those who bought the stock near the peak are now in a very bad slump, which they paid for because they were not aware of the fair value of the stock.
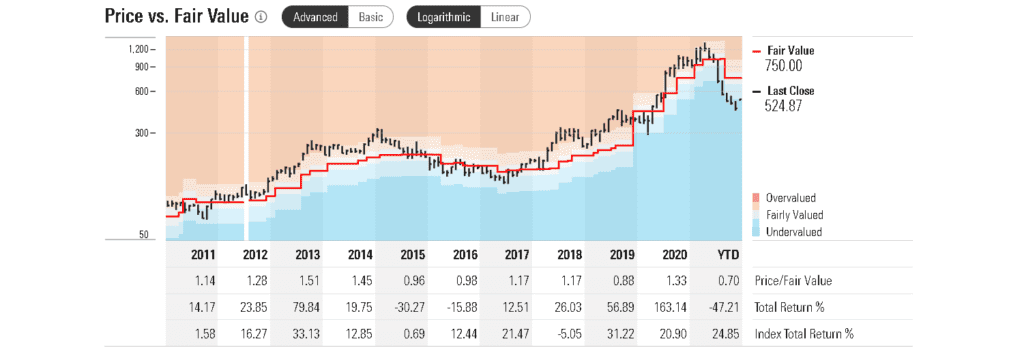
So, a fall only seems good to those who don't own the stock, but this still doesn't reveal what the real price of the stock is.
📌In practice: My biggest personal loss so far is PayPal, which I bought at the beginning of 2022 at a price of 146.65 USD. It is currently 69.14 USD, which is roughly a 63% loss, but the thing is not over yet. I will come back to this article in a few years and see how the stock's valuation has developed.
The case of PFE
Pfizer (Pfe) was not really doing well before the COVID pandemic. This is one of the reasons why Viatris outsourced it (VTRS) into a company called generic drugs. Such spin-offs often occur precisely because the parent company simply outsources unprofitable parts of the company in order to increase the efficiency of the remaining business units. Then the epidemic hit, Pfizer started producing vaccines and this was quite profitable for them. As the money poured in, $26 billion in revenue was generated from COVID vaccines alone, which is why the fundamentals improved, so the share price doubled in two years compared to March 2020. So the share price is currently on an upward trend, but does that make it a good buy?
Let's see what's happened since then, the COVID panic is over, but the company's internal operations and execution haven't really improved, so as soon as the surplus vaccine production ran out, the price crashed. For how long? Even further below the previous 30 USD price by 20% (as of June 2025). Trees don't grow to the sky, just as you can't produce an infinite amount of vaccine.
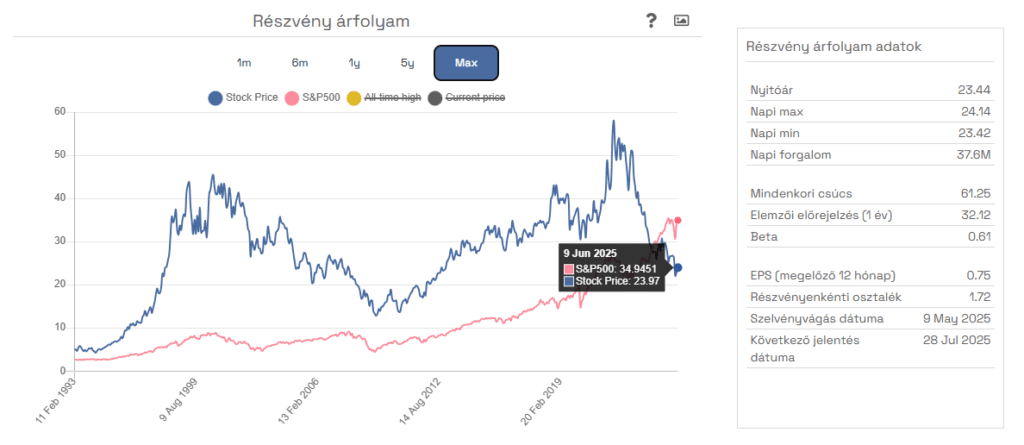
source: iO Charts
Here, I can say the same thing as in the case of SAM: you need to see the underlying fundamentals, the quantitative and qualitative elements, in order to draw actual conclusions about the valuation of a stock.
Yes, but how do we decide what the fair value of a stock is, since I listed three different examples above, yet I didn't draw any substantial conclusions from them. So let's look at some widely used methods for roughly determining the fair value of stocks, because no one has ever managed to do it exactly.
Stock valuation: long-term P/E averages
There are countless metrics used to determine fair value. A typical one is comparing the current P/E value to the 3-, 5-, and 10-year P/E averages, which is nothing more than dividing the price and earnings per share by each other and then averaging them over the above time periods. Of course, it doesn't matter what you compare the resulting values to. It's okay to use the company's current P/E average as a basis. If it's lower than the long-term average, the company looks cheap compared to itself. Of course, this doesn't necessarily mean that the company is cheap compared to the industry average, as there are companies that are always trading at much higher valuations than their peers. If you're a visual type, I recommend the Simply Wall St website, they use great diagrams to show you how much they think is enough. We also wrote a separate article on the interpretation and use of EPS and P/E metrics: Meaning and use of EPS and P/E ratios
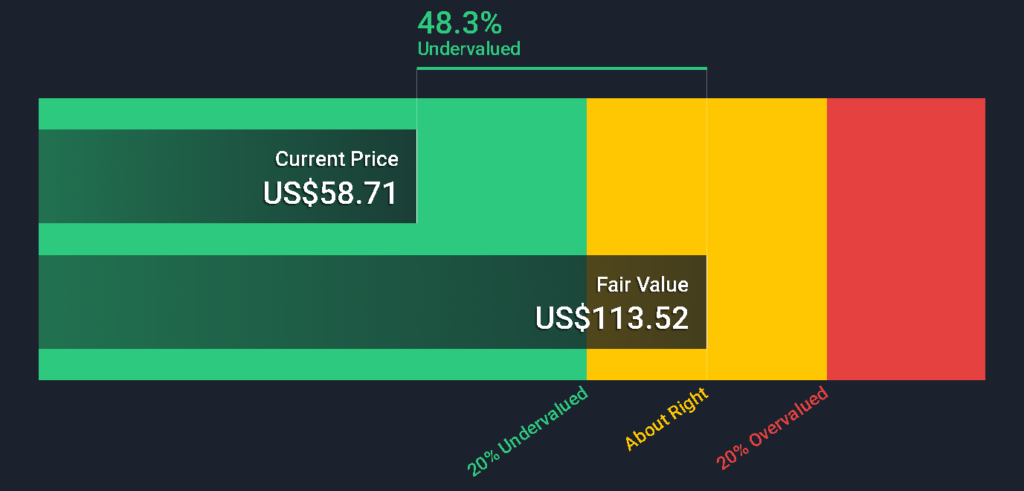
Speaking of PFE, it's worth noting that the pharmaceutical industry average traded at a P/E of 22.6 in 2021. In comparison, PFE is only 16.8, so it still looks relatively cheap in this comparison. To avoid misunderstandings, I don't think Pfizer is cheap, I'm not saying that, I just want to point out that PFE's P/E is lower than the industry average. It is worth adding the market average, which in the vast majority of cases means the average P/E value of S&P500 companies. This is 17.1 at the time of writing, and PFE's P/E falls below this number. This may give the false impression that since similar stocks are valued higher, PFE is relatively cheap.
The Graham number
Benjamin Graham is often referred to as one of the best investors of all time. He is also Warren Buffett's mentor, and the book The Intelligent Investor is also associated with his name. The Graham number was created by Benjamin Graham to express the fundamental value of companies, the exact formula can be viewed here: Investopedia - Graham Number.
The essence of it, in simple terms, is that it takes the P/E and the book value per share as a basis for determining the valuation. The formula also includes a number of 22.5, which is actually the decomposition of the product of 15×1.5. These are threshold numbers, and they symbolize Graham's belief that a company is cheap if the P/E metric is no greater than 15, while the book value is less than 1.5. With this, Graham established two values that have been referred to ever since when they want to express the valuation of a company. I mainly come across P/E=<15, book value is now much less applicable to modern companies than, say, 50-60 years ago.
✨A small digression: the literature calls this type of valuation method the asset value principle. This is nothing more than a value calculated from the value of a company's total assets, assets and liabilities, at a given point in time.
But back to the Graham number. If you read somewhere that a company's P/E number is higher than 15, then it is considered expensive, then this statement can probably be traced back to the Graham number equation. Of course, here too, we must take into account what we are comparing the P/E=
Stock valuation: the dividend yield theory
Dividend metrics have a very simple pitfall: not all companies pay dividends. In other words, companies that do not pay dividends are excluded from this type of valuation metric. It is a great advantage if the company has been paying dividends for 10-15 or more years, because a short dividend history can lead unsuspecting investors to very false conclusions. A good example of this is Medifast (MED), whose dividend has increased by 560% over an eight-year period. Obviously, the company will not maintain the same rate of increase for the next 20 years, but I think the point is clear from the example. The longer a company has a history of dividend increases, the easier it will be to draw conclusions about its valuation.
☝🏼The dividend yield theory was first used by a fund manager in the 1960s, and was featured in the Investment Quality Trends, or IQ Trends, newsletter. It gained real popularity in the 1990s with the publication of the book Dividends Don't Lie: Finding Value in Blue-Chip Stock by Geraldine Weiss-Janet Lowe.
In the 2010s, Kelly Wright, then-editor-in-chief of IQ Trends, updated the basic thinking in her book Dividends Still Don't Lie. Read them if you want, but if you don't, there's a great summary on the Simply Safe Dividends website, which I found here: Dividend Yield Theory Summary.
The essence of Dividend Yield Theory
Basically, the method can be applied to blue-chip, i.e. long-established, well-known companies. These are very predictable companies, their pricing fluctuates cyclically around a relatively fixed average value compared to the dividend, to which they always return, but sometimes their price is higher and sometimes lower, and this is exactly the average value we are looking for. There are also other connections, for example, that rising profits also pull the share price with them, meaning that it will also rise. Mature, dividend-paying companies tend to pay a significant part of this profit to their owners. Dividends are also good because it is very difficult to fake its size, since it is transferred to the owners, meaning that only existing cash flow can form its basis.
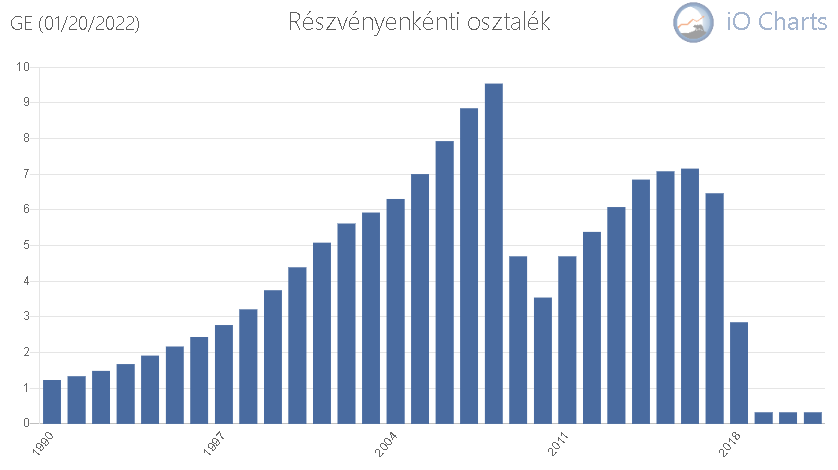
💡From the above, it follows that there must be some correlation between the price of a stock and the amount of dividends paid. Since there is an inverse relationship between the price and the dividend payout ratio, i.e. the lower the price, the higher the percentage value and vice versa.
It is easy to conclude that if the dividend yield is high, the company is undervalued, and if it is low, it is overvalued. Of course, this is not just something IQTs tell us, there is also empirical research to support it: Dividend Yield Theory
Limitations of Dividend Yield Theory
The first and most important thing is that if a company does not pay dividends, then the method cannot be applied to it, such as Tesla (TSLA) or Paypal (PYPL). It should also be remembered that this is essentially applicable to mature, long-term dividend-paying companies. What IQT considers a mature company is derived in a precise manner, for example, one of the criteria is 25 years of uninterrupted dividend payments, which is what the previously mentioned Medifast (MED) for example, cannot fulfill.
☝🏼However, I think there is a bigger problem with the model, and that is that there are many companies on the market where dividends only account for a very small part of the total return.
For example, Microsoft (MSFT) or Apple (AAPL) dividends add almost nothing to the total return, yet these companies are growing at a brutal pace. In this case, it is obvious that their valuation cannot be determined solely by the amount of dividend payments, as this is not the main driver of valuation. They intentionally do not pay out a significant portion of the profits they generate, but instead reinvest it into growth, where they can achieve a higher return.
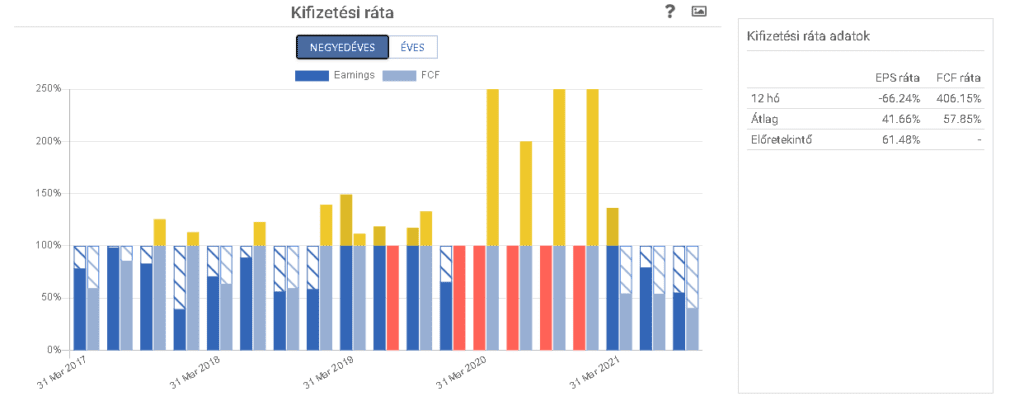
Let's look at the opposite, when the company pays out too many dividends, which results in an extremely high payout ratio and therefore a high dividend yield. In many cases, this simply means that the company is overstretching its financial capabilities and is inevitably moving towards cutting dividends. This was the case for General Electric around 2017, but Exxon (XOM) was also very close to this between 2020-2022. Since the oil company financed its dividend payment with debt during COVID, since it did not have much income, the high dividend yield apparently assumed undervaluation, but the fine print was that this included the possibility of a dividend cut, which ultimately did not happen.
Contradictions of Dividend Yield Theory
Let's say a company's stock price is being beaten down by the market. Let's also assume that the stock is trading at a price of $100 and a dividend of $5, with a dividend yield of 5%, but then a panic occurs and the stock price is halved. The company's fundamentals are not at risk, and it continues to pay a dividend of $5, but the dividend yield now rises to 10% due to the price change. In this situation, would it be a logical decision for the company to, say, buy back shares instead of paying out the dividend?
Probably yes, since with the decreasing number of shares, they would also have to pay fewer dividends, meaning they would reduce costs, and share buybacks also create shareholder value, in many cases driving up the share price, and it would be cheaper to pass this increase on to shareholders. However, if the company were to avoid this, many investors would turn away from them, since they bought the stock precisely for the predictable cash flow, and they would like to continue to collect the $5 per share. Therefore, the model is best suited to slow-growing, stable companies, such as utilities, real estate management companies, and certain food companies.
I very rarely buy such companies for the above reasons, as most of the total return potential comes from dividends. Since there is not much organic growth in the companies, the total growth will also be low and will even generate costs due to taxation. Of course, another question is whether if the market really pushes down the price of a stock, you can bet that the valuation will rebound, meaning that you can realize a price gain, and this will be the main driver of the return. In this case, of course, a higher-than-average dividend yield can help you find stocks that are trading below fair value.
The discounted cash flow model, aka DCF
If there is a Holy Grail when it comes to stock valuation, it is the DCF model; almost every major website has a value determined using this method. I mentioned earlier that there are asset-based models that look at a company's assets and liabilities, such as book value. The big problem with these models is that they don't take into account the time value of money. This means that $100 produced today won't be worth the same a year from now because its purchasing power will have decreased. The discounted cash flow model does nothing more than calculate the expected cash flow over a predetermined period, usually 5 years, and then discounts it back to its present value. Here you will immediately encounter two problems: how long the discounted time period should be, and what is included in the cash flow.
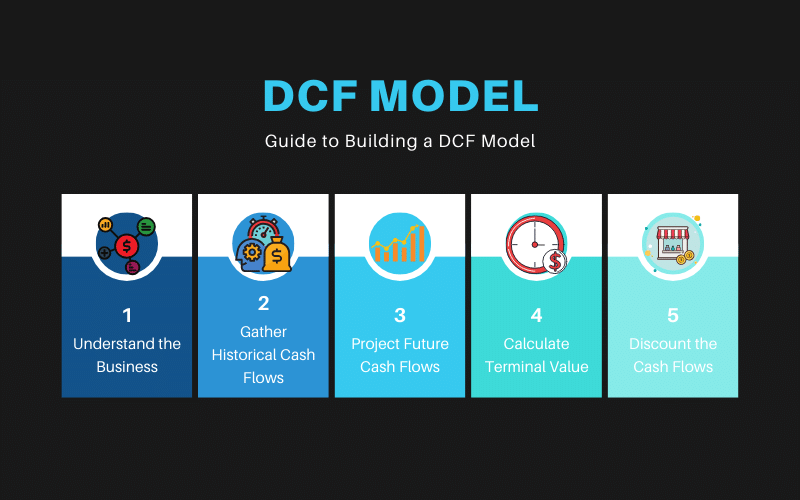
Before everyone gets too excited, I'll tell you that I don't usually calculate the value of companies based on the DCF model either, but if you want to delve deeper into the matter, check out the Investopedia article: DCF meaningIf you would like to create an Excel spreadsheet for this, the following article will also be useful: DCF Model Training Free GuideWe won't do that now, and I'll tell you why. The first and most important reason is its complexity. I'm almost certain that 99% of readers will not start calculating DCF, and the remaining 1% will give up when they realize how much of a difference changing an input parameter will cause in the output values.
The DCF model is a bit like the city-viewing telescope on top of the Citadel. While you're at single magnification, you can scan the entire area, but you can't see the details. When you zoom in on the image, the details come out, but even with a very small movement, the image jumps so much that you don't know where you are. Unfortunately, this is true for all similar models, as they can only provide a maximum approximation of a company's value.
Economic Value Added, or EVA
The EVA framework is a value-added type of methodology. Its basic assumption is that the value-creating ability of companies is not reflected in systems based on accounting data. I have already written about this in several articles, the gist of which is that these are very difficult to demonstrate properly according to accounting rules. These include, for example, management performance, the company's capital allocation, how the cash generated is spent, etc. In addition, management can manipulate accounting data, which is what EVA tries to eliminate.
How can I access EVA data?
- ✨The system is quite complicated, but there is an unreadable book: Economic Value Added (EVA): The Company Performance Predictor.
- ✨Limited EVA data is also available to anyone who has an Interactive Brokers account, where you can find quite a lot of data.
- ✨There is a Hungarian-originated, but international newsletter that works with EVA data: The Falcon Method.
The reason I wrote the above is very simple: to my current knowledge, there is no better approximation system that can properly evaluate companies. Calculating their metrics, however, is terribly complicated. It is much easier to buy a part of the services, where this time-consuming and tedious work is simply done by someone else for me.
What do well-known sites say?
There is another very simple way to determine the approximate fair value of stocks. You simply need to look at the fair values calculated by major investment sites and average them. BUT, before you blindly believe this, I will share with you some of my own experiences and the list of sites I have tried on this topic so far:
- 📚Morningstar: When analyzing the given companies, there is a fair value indicator and a ten-year valuation graph, where the values can be viewed retrospectively.
- 📚Gurufocus: There is a DCF-based fair value indicator calculated by them, and a Peter Lynch valuation chart on the main page.
- 📚Simply Wall St.: a real value indicator calculated by themselves, but I think artificially generated, the description of which is also available.
- 📚Simply Safe Dividends: The site provides a textual, IQT-based, dividend-based fair value calculation.
- 📚Alphaspread: They also stop at three real values, based on 3 scenarios, meaning they actually define an interval.
- 📚Other pages: I can mention Substack and Seeking Alpha analyses, but they are quite unreliable.
📌In practice: In my stock analyses, I usually take the average of the fair values of the above pages as a basis, and then, with a safety margin, draw an interval based on which I determine the fair value. Why do I do it this way? Because there can be errors in any calculation. The already mentioned The Falcon Method also determines several entry prices, and even though they are professionals and make a living from this, they still determine the prices as an interval. Moreover, the fair value moves with the company's fundamentals, meaning that if they deteriorate, the fair value also slides down, while if they improve, it moves up. You can also see this averaging in stock analyses: iO Charts stock analyses.
Are these calculated values reliable?
Before anyone blindly relies on the methods used to value stocks, I unfortunately have to debunk them, because sometimes the different sites show completely different things. The variance is huge, and in my experience, the artificially generated real values show an even messier picture than usual. Simply Wall St. often comes up with completely incomprehensible numbers, for example, according to them, Pfizer was worth 113 USD a few years ago, while Morningstar says it was 44. Simply Safe Dividends only gives a text tip on whether a company is undervalued or overvalued based on the dividend yield and P/E ratio.
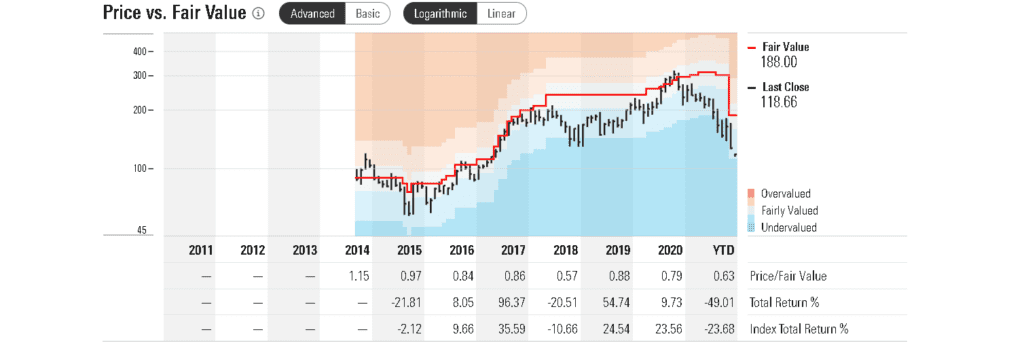
The values of Morningstar and Gurufocus are much more interesting, I'll start with the former. MS fair value is generally quite good, but the site has a rather big flaw, which is also its advantage, the fair value tracks the company's performance very quickly. What do I mean here? The values of the companies are automatically revised after each quarterly analysis. For example, in the case of a prosperous growth stock, the excess performance is quickly incorporated into the price.
This is completely justified, as there are companies that, even looking back 10 years, could hardly be purchased below fair value because it is constantly rising, an example of this is Monster Beverages (Mnst), Visa (V) or Mastercard (MA). Unfortunately, this approach is also used when companies' value decreases. I find it a bit strong that a company's real value fluctuates by 20-30% in a quarter. I think they are changing these numbers unreasonably quickly.
📌In practice: Why is it so difficult to buy the best companies below fair value? Because these companies perform so well and surprise so much more positively than the market expects, that even when their valuations skyrocket, they continue to grow along with them. The Falcon Method calls these companies EVA Monsters, which have such a high intrinsic value creation capacity that their performance consistently beats their valuations, making them worth holding at fair value.
Stock valuation: the Peter Lynch graph
GuruFocus has a very interesting graph that shows both the past and the future. You can read a lot from it, I usually use it together with Morningstar's values, but their Peter Lynch scale on the main page is much more interesting.
Peter Lynch: a fairly famous American investor, manager of Magellan and Fidelity Investment funds. He wrote books such as Success in the Stock Market. He is a committed believer in value investing, who created the Peter Lynch chart named after him. He did nothing more than plot the price and the earnings per share on a coordinate system. They often also add the dividend per share, and typically choose quite long time periods so that the trend can be followed. This is actually nothing more than a P/E chart, only the two values are represented by a graph.
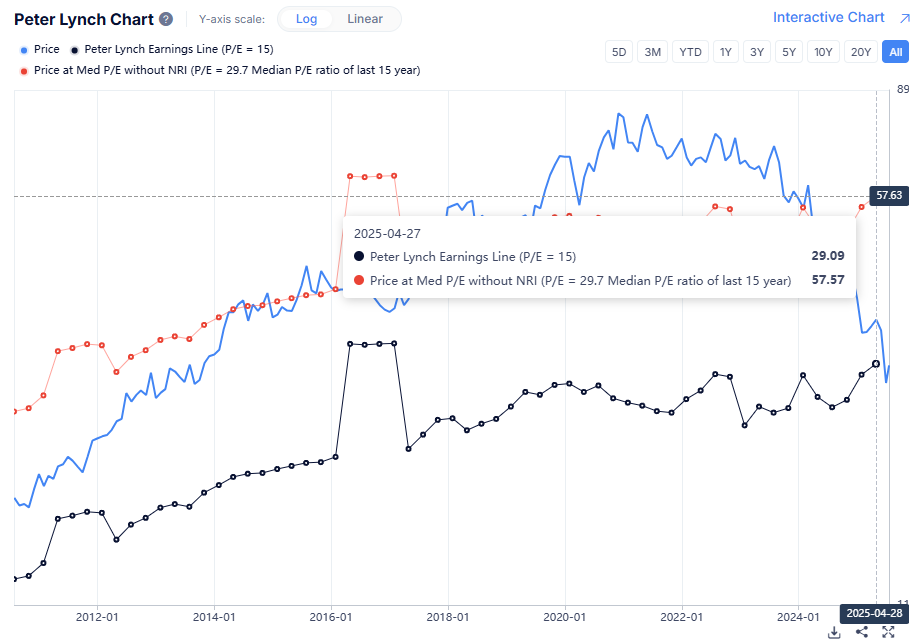
Why is this good? Because you can see at a glance where the two lines intersect. If the earnings per share are higher, the stock is undervalued. If the price is higher, the stock is overvalued. It's as simple as that. Of course, this is not something set in stone. Since I'm a visual person, I can easily read the company's approximate valuation. If it's overvalued, I usually don't look any further, so it can be used as a great pre-filter.
Final Takeaway
Stock valuation is a relatively difficult topic to digest. What is certain is that without this, it is very difficult to make appropriate investment decisions and make a profit. Overpaying can cost you a significant portion of your profits, and the same goes for a sell that is made at the wrong time or at the wrong time. For me, this is probably the most complicated part of investing, but hopefully I have helped you get a handle on it. The important thing to remember is that you will never know the exact value of a stock. Where you buy or sell will depend on your personal preferences.
🤑If you are interested in what brokers we use, read our articles below:
(I.e.Interactive Brokers broker account analysis – Professional for professionals
📈LightYear Broker Account Analysis - Simplicity and cheapness go hand in hand
Frequently Asked Questions about Stock Valuation
Answers to the most common questions
Can't decide if a stock is cheap or expensive? Here you'll find concise answers to the most frequently asked questions: what does valuation even mean, can it be read from a stock chart, what is the P/E ratio, what is the Graham number, DCF and EVA, and how reliable are the fair value numbers on major investment websites?
Click on any question and the answer will open. These are intentionally short summaries: if you are interested in the details, I will expand on them in more detail in the appropriate sections of the article. The most important thing to know in advance: no one can determine the exact value of a stock, all methods only give an approximation.
What does stock valuation mean?
Valuation seeks to answer the question of whether the current price of a stock is below, above, or close to the true, underlying value of the company. It is important to separate it from price: price is what you pay, value is what you get. In practice, no method gives an exact number, only a range to which you should apply a margin of safety according to your own beliefs.
Does it matter whether a stock falls into the “growth” or “value” category?
These are primarily labels, not literary categories. A company that is growing rapidly, paying dividends, and dominating its market could fit into more than one box at once. The classification is dangerous because it builds different expectations in the investor: many people accept the high pricing of a “growth” stock simply because of the label. A much more useful framework is the corporate life cycle model, which shows whether a company is in the early growth, mature cash cow, renewal, or decline stages.
Can the valuation be determined from the exchange rate chart?
No, and this is one of the most common mistakes. Just because a stock has fallen a lot doesn't mean it's cheap, and just because it's risen a lot doesn't mean it's expensive. The price movement doesn't reveal the underlying event that caused it: a 50% drop could mean that an unjustified growth premium has ended, but it could also mean that the company's fundamentals have deteriorated. You should always include the numbers and qualitative factors alongside the graph. It's also worth remembering that a 50% drop requires a 100% increase to offset a 50% drop.
What is the P/E ratio good for and what is it worth comparing it to?
AP/E is the price divided by earnings per share. It doesn’t say anything on its own, it can only be interpreted in conjunction with a benchmark, and it’s worth looking at all three: the company’s own 3-, 5-, and 10-year historical average, the industry average, and the market average (typically the S&P 500). Just because a company is cheap relative to its own history doesn’t mean it’s cheap relative to its peers — there are companies that consistently trade at higher multiples than their peers.
What is the Graham number and where does the P/E 15 rule come from?
The Graham number was created by Benjamin Graham, Warren Buffett’s mentor, to express the fundamental value of companies. The formula is based on P/E and book value per share (BVPS), and includes a multiplier of 22.5, which is actually the decomposition of 15 × 1.5. These two thresholds reflect Graham’s belief that a company is cheap if its P/E is no more than 15 and its BVPS is no more than 1.5. If you read somewhere that a P/E above 15 is considered expensive, that’s almost certainly where it comes from. Book value is much less applicable to modern, asset-light companies than it was decades ago.
What is dividend yield theory and when does it not work?
Dividend Yield Theory assumes that the pricing of a mature, long-standing dividend-paying company fluctuates cyclically around a relatively stable average dividend yield. Since there is an inverse relationship between price and dividend yield, a yield higher than the historical average indicates undervaluation, while a yield lower than the historical average indicates overvaluation.
It can't be used in three situations. If the company doesn't pay a dividend, it's out of the picture. If the dividend is only a tiny fraction of the total return—as in fast-growing, reinvesting technology companies—it's not a driver of valuation. And if the payout ratio is overstretched, a high yield isn't a sign of cheapness, but of an impending dividend cut.
What is the DCF model and why is it difficult to use?
The discounted cash flow model calculates the company's expected cash flows over a predetermined period of time and then discounts them back to their present value — thus taking into account the time value of money, which asset-based methods do not. In theory, this is the most thorough approach.
The practical problem is the sensitivity of the input parameters: even a small change in a single assumption causes a huge difference in the final result. It's like a telescope: the more you zoom in, the more detailed the image, but the bigger it jumps to even a small movement. That's why DCF only gives an approximate result, not an exact price.
Are the fair value numbers on major investment websites reliable?
Limited. The spread between them is huge: one site can give two or three times the price of the other for the same stock. Fair values generated automatically, without any analyst work, are the least reliable — they should be treated with caution. Hand-analyzed estimates are more useful, but even with these, you should be aware that many providers revise the number after each quarterly report, so a company's "real value" can fluctuate by as much as 20-30% from quarter to quarter, which is thought-provoking in itself. The most useful approach is to average multiple sources and then apply your own safety margin to this.
Legal and liability statement (aka. disclaimer): My articles contain personal opinions, I write them solely for my own entertainment and that of my readers. The articles published on iO Charts do NOT in any way exhaust the scope of investment advice. I have never intended, do not intend, and am unlikely to provide such in the future. The information provided here is for informational purposes only and should NOT be construed as an offer. You are SOLELY responsible for the decisions you make.